Spotlight On: Will Pyle, Market President, Hancock Whitney
Key points:
- • Hancock Whitney is focused on growing loans, deposits, and client relationships in North Texas.
- • Local businesses are deploying sidelined capital despite higher borrowing costs.
- • The bank aims to be America’s best bank for privately owned businesses.
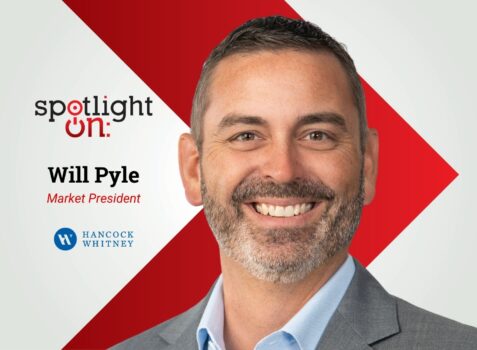 October 2026 — In an interview with Invest:, Will Pyle, Dallas market president at Hancock Whitney, discussed the bank’s North Texas growth strategy, businesses’ willingness to invest, and the role of local bankers in a digital environment. Pyle emphasized accountability in client relationships: “The bank empowers associates to own situations, good or bad, and work with clients through to the end,” Pyle said.
Join us at caa’s upcoming leadership summits! These premier events bring together hundreds of public and private sector leaders to discuss the challenges and opportunities for businesses and investors. Find the next summit in a city near you!
How would you describe Hancock Whitney’s position in North Texas today?
Hancock Whitney has more than 125 years of history serving its legacy markets. We’ve had a formal branch presence in Dallas-Fort Worth since 2019. I’d describe us as a newcomer to this market with significant strength and resources behind us.
What are your main priorities for growth in the region?
There are measurable priorities: growing our loans, deposits, and relationship portfolio in the North Texas communities we serve. But growth also means bringing in the right people, with an entrepreneurial spirit, who want to help build something. Then we work together to bring the bank’s existing culture and add our own approach to strengthen it further. The goal is a great client experience for both commercial and retail clients.
What differentiates the bank in such a competitive market?
The last FDIC data I saw showed 170 banks participating in Dallas, excluding nonbank lenders. It’s an extremely competitive market.
We offer relationship banking with decisions rooted in common sense. If an opportunity makes sense, we try to bring our resources to it. Some opportunities don’t fit the bank’s culture, and another institution may be better suited to them.
We have a strong desire to grow here. We recognize the power of the Dallas-Fort Worth economy, with more than eight million people and tremendous opportunity. The bank wants to keep growing in Dallas and across Texas. My job is to build on our success in the Dallas market.
What are you hearing from business owners about confidence and investment?
In late 2025 and early 2026, clients paused somewhat to see how broader economic changes would affect their businesses. Now, we’re seeing something closer to business as usual, with an understanding that some assumptions have changed.
We’ve just seen a rate increase, and borrowing costs have been higher for several years. That affects clients, how they pay, and what gets charged to the end user. Businesses seem to be factoring those costs in.
I wouldn’t say the low-rate days are permanently behind us, but people aren’t expecting an immediate return to them. We’re seeing more confidence and willingness to invest in companies. Money that had been sitting on the sidelines is starting to be deployed more.
Which industries and commercial real estate trends are creating opportunities?
Dallas-Fort Worth’s diverse economy gives us a diverse portfolio. We work across many industries rather than focusing on one. We particularly like business-to-business activity, healthcare, and manufacturing — businesses that make something for someone else.
In commercial real estate, high-level professional investors remain strong. They adjust their equity positions, and entering a project at the right cost tends to support success.
We’ve seen some stress among people who entered when prices were elevated and borrowing costs were low. Our bank remained disciplined and avoided those situations, so we haven’t really been affected by that adjustment.
Even in Dallas’s office market, I see more people returning to work. From my office, I used to see several vacant floors in the building next door. Now, I see occupied floors or construction. That’s a small sample and a personal observation, but I think it reflects something happening more broadly.
What are privately owned and middle-market businesses looking for from their bank?
Most people want a trusted advisor to guide them through lending. That’s a principle we use in recruiting: We want associates clients will see as trusted advisors.
The bank also brings in partner business lines, whether treasury management, wealth, equipment finance, or our ABL group. We surround clients with a team of experts.
I don’t think we’re the only bank doing that. But I think we do it better than just about anybody, and those teams bring considerable expertise to a transaction.
Why do local relationships still matter, and how do you attract and retain bankers?
There’s a major emphasis on digital banking. But when making important financial decisions, clients want to speak face-to-face with a banker they know and trust.
Employees also want to feel part of something. The bank explains its broader vision and each associate’s role, then gives them room to chart their own course toward their goals.
Our Dallas-Fort Worth bankers are entrepreneurial and building something. They get recruiter calls, but they tend to be rooted here because they’ve built their businesses. Combining that with common-sense credit decisions helps us win, which associates enjoy.
How is technology helping the bank address fraud?
We partner with our treasury team, which uses tools such as AI to identify potentially suspicious transactions and protect commercial clients against fraud.
We regularly see transactions paused for verification. The bank is putting processes in place to identify a concern, temporarily stop the transaction, involve a person, and verify that we’re speaking to someone authorized on the account.
Fraud changes constantly. We use our resources and external partners to keep up.
What makes North Texas attractive to businesses and employees?
It’s a combination of space, room to grow, and a pro-business economic climate. Dallas-Fort Worth attracts new companies and people relocating, and I feel it’s leading in many areas of corporate growth.
A fairly reasonable cost of living also appeals to people moving here. The heat in August and September gets complaints, but the rest of the year is generally pleasant.
Our transportation connections make it relatively easy to reach other parts of the country and the world. The region feels positioned to keep growing. I see it outpacing other major metropolitan areas.
What indicators are you watching as you look toward 2027 and beyond?
We watch macroeconomic indicators, with analysts tracking trends in the markets we serve. We also review our portfolio and publish information about peers’ portfolios to make sure we’re not overlooking something.
When we notice common trends, we investigate who else might be affected. That leads to conversations with clients about whether they’re seeing the same thing and can help them prepare for, or possibly avoid, industry challenges.
There isn’t one indicator we watch. Activity levels matter, too. If business slows, we ask what’s causing it. A broad range of information is reviewed at my level and above.
What are your priorities over the next few years?
My mission in North Texas is to support the bank’s goal of becoming the best bank in America for privately owned businesses. We’re pursuing that by bringing new relationships to the bank.
We believe we can offer services in line with, or better than, many larger banks in the market, while providing more service than smaller banks. We want to position the bank to deliver on that goal.
Want more? Read the Invest: Dallas-Worth report.