The potential beneficiaries as defense manufacturing surges
Key points:
- • Record $961B+ defense budget is driving job growth across key US tech and manufacturing corridors.
- • Severe labor shortages and 70k+ open security clearance roles threaten execution despite $127k+ average pay.
- • Regional hubs from Boston to Florida expand, but 90% of executives report difficulty hiring skilled talent.
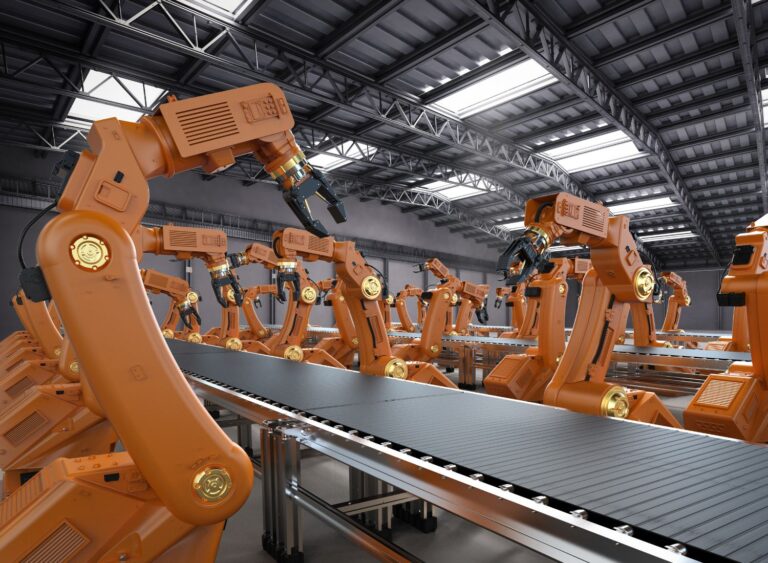
 October 2026 — Defense manufacturing is driving a jobs surge in the United States, and those regions already set up to serve could be among the biggest beneficiaries. The challenge, however, remains the same across manufacturing: finding the right people for the job.
Join us at caa’s upcoming leadership summits! These premier events bring together hundreds of public and private sector leaders to discuss the challenges and opportunities for businesses and investors. Find the next summit in a city near you!
“The skills gap is one of the biggest challenges in manufacturing,” said Lisa Masciantonio, CWO at the Advanced Robotics for Manufacturing (ARM) Institute, in a recent interview with Invest: Pittsburgh. “We cannot rely on one solution; we need to encourage more people to enter the field while also using automated solutions to fill jobs that we know may never be filled, retain and upskill current workers, and attract more job-ready individuals.
While Masciantonio was speaking to manufacturing in general, her remarks apply just as well to the defense industry
Amtec calls workforce availability in the sector the “binding constraint” on sustaining growth and puts industry attrition near 15%.
As defense budget soars, who benefits?
The federal budget is the main driver of demand for defense manufacturing jobs, with the enacted FY2026 defense budget totaling $961.6 billion, a 13.4% increase over FY2025. The White House proposed $1.5 trillion for FY2027 in April, subject to congressional action. Area Development calls the result “a capital formation environment without modern precedent.”
Breaking it down, the Navy alone plans to invest more than $6.2 billion to expand and stabilize the submarine industrial base. Deloitte’s midyear update says defense priorities now favor munitions, drones, missile defense, space, cyber, and industrial-base expansion. The Trump administration invoked the Defense Production Act for munitions, and multiyear framework agreements give suppliers longer demand visibility.
The industry’s base is large. The Aerospace Industries Association (AIA) counts $988.6 billion in 2025 sales and 2.1 million supported jobs, with Florida among the Top 5 states for employment.
While Florida and its Space Coast (Cape Canaveral to Melbourne) might seem a leading beneficiary of higher defense spending, it is not alone. Other key regions that stand to benefit are Boston and Pittsburgh in the North, Greater Philadelphia and New Jersey in the mid-Atantic, and South Carolina rounding out the South with Florida.
The high-tech North
At the northern anchor of the corridor, Boston and Pittsburgh operate as dual engines for next-generation defense technology. Boston’s ecosystem, driven by MIT Lincoln Laboratory, Draper Laboratory, and major prime contractors like RTX, acts as a primary magnet for microelectronics, radar hardware, and dual-use AI investments. This concentration sustains robust demand for secure, specialized flex facilities (SCIFs) and R&D lab space along the I-495 and Route 128 belts.
Meanwhile, Pittsburgh leverages academic powerhouses like Carnegie Mellon University to lead in military robotics, autonomous ground vehicles, and software architecture. Heightened defense spending accelerates DoD grant allocations to regional tech spin-offs, driving venture capital activity and tightening the market for specialized manufacturing space.
The heavy mid-Atlantic
Moving into the mid-Atlantic, Greater Philadelphia and New Jersey capture the operational core of heavy industrial procurement and C5ISR (Command, Control, Communications, Computers, Cyber, Intelligence, Surveillance, and Reconnaissance) development.
Greater Philadelphia benefits directly from large-scale platform production, where facilities such as Boeing’s Ridley Park plant, which handles production and modernization for heavy-lift rotorcraft like the CH-47 Chinook, drive significant demand across local industrial supply chains and precision machining networks.
Parallel to this hub, New Jersey occupies a vital niche in weapons research and military communications. Anchored by Picatinny Arsenal and a dense network of Tier-1 defense contractors, the state’s defense corridor channels federal funding directly into high-wage engineering roles and specialized munitions manufacturing across Morris, Monmouth, and Burlington counties.
The tactical South
The Southern markets — the Space Coast/Central Florida and the South Carolina Corridor — anchor the deployment of space defense, tactical systems, and logistics. Florida’s Space Coast, stretching from Cape Canaveral to Melbourne, and the nearby Orlando metro area experience a compounded surge from DoD procurement and Space Force expansion.
While Melbourne-headquartered L3Harris Technologies and missile manufacturers scale satellite and rocket assembly along the coast, Orlando remains the national center for military modeling, simulation, and training (MS&T) software contracts.
South Carolina’s corridor, stretching from Upstate to the Lowcountry, serves as a major tactical export and logistics node. Lockheed Martin’s facility in Greenville serves as the global production hub for the F-16 Fighting Falcon. Combined with military ground vehicle production and the logistical engine of the Port of Charleston, the region attracts heavy capital investment in industrial park infrastructure.
Labor sets the ceiling
Filling defense manufacturing jobs is the constraint. Some 90% of defense executives report difficulty recruiting for current needs, and 43% rank workforce availability first in location decisions. Deloitte adds that some expanding maintenance shops lack enough certified labor, test cells, and tooling.
The gap will widen. US Defense Group estimates the sector needs 250,000 more workers over the next decade and argues the central constraint is no longer simply funding but execution capacity. The submarine industrial base shrank from 17,000 suppliers to 5,000, and nearly 70% of the remaining workforce nears retirement.
Amtec counts more than 70,000 unfilled security-cleared positions, a 2023 estimate it says likely runs higher now. It also cites an analysis that Golden Dome alone would require a 30% to 40% larger skilled labor pool. Pay alone will not close the gap. AIA reports average industry wages above $127,000, about 40% over the national average.
The Center for Strategic and International Studies counts roughly 10,000 new firms in the defense market over two years. Nontraditional companies received more than $120 billion in FY2025 contract obligations, and Foreign Military Sales topped $80 billion. Rare earth production rose from 95 tons in 2022 to 8,900 tons in 2025. Study co-author Jerry McGinn says “the trends are moving in the right direction,” though lead times and stockpiles still lag.
Defense tech venture deals also hit a record $19.8 billion in 1Q26, up 146% year over year. Aerospace and defense capital spending reached $45 billion in 2025, up 13%. A pending Ships Act would add a 25% federal tax credit for shipyard investment.
Some 98% of related defense industry executives surveyed in a white paper compiled in collaboration with the Michigan Economic Development Corporation said they are preparing to localize or reshore supply chains, and 88% call regional innovation corridors critically important. Retired Col. John T. Gutierrez, U.S. Marine Corps, executive director of Michigan’s Office of Defense and Aerospace Innovation, says the future favors the most integrated region over the lowest-cost one.
Want more? Read the Invest: reports.